

Bank-grade capital that scales with your business.
Invoice finance, business loans and embedded credit for established UK businesses. Bank pricing, delivered at a fintech's pace.
- Keeping business flowing brilliantly since 2012
- £4bn+ credit advanced to UK businesses
- Part of Allica Bank
Trusted by ambitious businesses since 2012




Why finance teams choose Kriya
Pricing
Funded at a bank's cost of capital, and priced accordingly.
Speed
Onboard in one week, with funds in your bank account in 24 hours.
Reliability
Invoice finance market leaders since 2012, now part of Allica Bank.
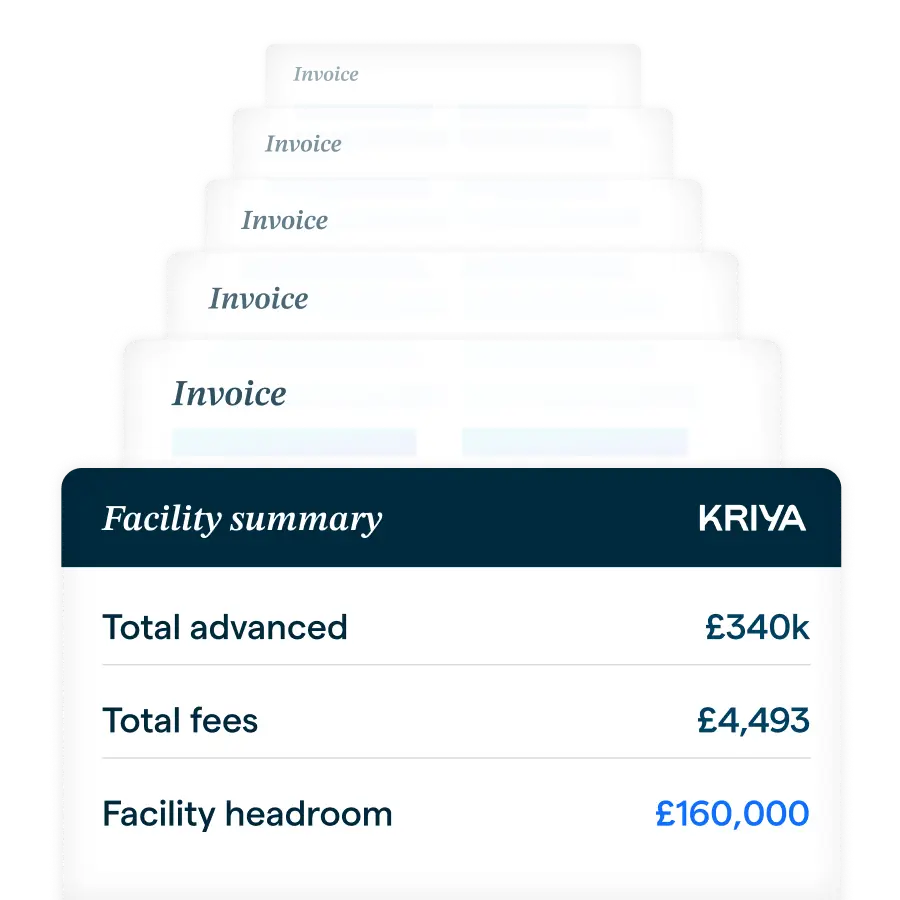
Unlock funding as you invoice
Scalable. Facilities that grow with your sales ledger, from £500K to multi-million.
Competitively priced. Bank-backed funding without the fees of a standalone lender. Service fees from 0.25% and discount fees from 2.5%.
Flexible. Put through as much of your ledger as you choose, with full visibility in your Kriya portal.
Why merchants work with us
Invoice Finance
AK9 Security & FM Solutions – £20.8m turnover in 2025 and 700+ staff paid weekly, funded by a £1.5m invoice finance facility while clients pay on extended terms.
Read the storyFinance your next move
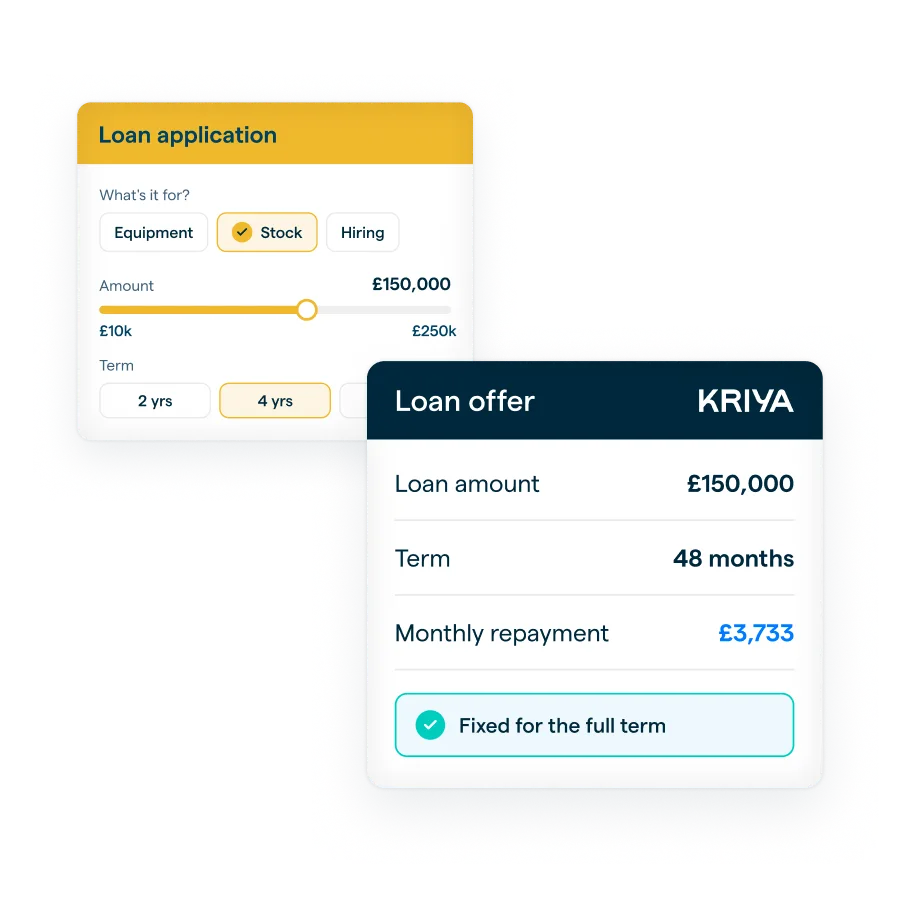
Term lending for acquisitions, capex and refinancing. Borrow up to £250,000 over 6 years with a Kriya Top Up Loan.
Take advantage of the Growth Guarantee Scheme through Allica Bank.
Why merchants work with us
Business Loans + Invoice Finance
Amber Labs – 120+ consultants and £20m–£25m annual revenue, scaling into government and defence contracts with long procurement and payment cycles.
Read the story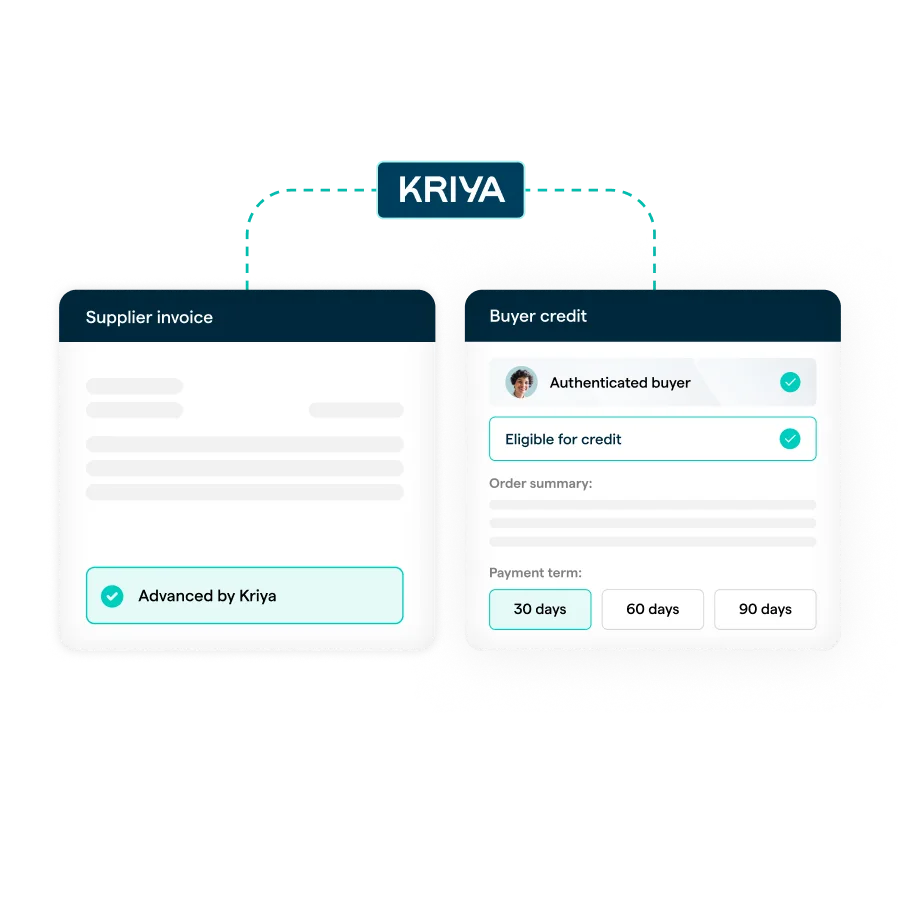
Embed credit for your buyers and suppliers
Kriya’s tools make it easy for you to offer credit, both online and offline.
Unlock purchasing power for your buyer base, with our lower interest rates, enabled by Allica Bank.
Why merchants work with us
A fintech’s speed. A bank’s balance sheet.
As of October 2025, Kriya is owned by Allica Bank, the UK’s fastest growing business bank. Together we aim to deploy £1 billion into UK businesses over the next three years.
Learn how the deal benefits youLet’s find the right facility for you
Takes about a minute to fill out. A member of our team will then reach out to set up a 20-minute call at a time that suits you.
- 1A short consultation focused on your goals and funding needs
- 2A clear view of whether Kriya is the right fit
- 3Indicative terms and a path to getting funded
Kriya’s promise. If we can’t help you, we’ll do our best to refer you to a trusted partner that can, no strings attached.
Questions about Kriya
Invoice finance. You draw down against invoices you've already raised, so the cash arrives when you deliver rather than when your customer decides to pay.
A loan. For stock, materials or a short-term gap, a working capital loan is usually the fit and is normally repaid within a year or two. For equipment or anything you'll own for years, a business loan matched to the life of the asset will usually cost less.
Embedded finance. Your buyers get the terms they're asking for, you're paid in full as soon as the order is delivered, and we handle the credit checks and the collections.
Invoice finance advances money you're already owed, so the amount available moves with your sales ledger and there's no fixed repayment schedule. A loan is a fixed sum you borrow and repay over an agreed term, whether or not your sales change. If the cash is already earned, invoice finance is usually cheaper. If you're funding something before the revenue exists, you need a loan.
Yes. Invoice finance and a loan can run side by side under one relationship and one underwriting process. Amber Labs uses both.
Often, yes. It depends on what your existing lender holds security over and whether their agreement allows a second facility. Tell us who you're with and we'll tell you quickly whether it works.
With invoice finance, yes. The facility is secured against the invoices you raise, so the more you invoice, the more funding is available, without a new application. A loan is a fixed amount agreed up front.
Most of our customers' annual turnover generally ranges from £1m to £25m. There's no hard cut-off in either direction, so if you sit outside that it's still worth a conversation. If we can't help, we'll point you somewhere that can.
Not unless you want them to. Confidential facilities are available, and you keep the customer relationship and collections.
With invoice finance, you do. You keep the relationship and the collections, so nothing changes from your customer's point of view. With embedded finance it's the other way round: we chase and collect, so your team doesn't.
With invoice finance, an invoice that goes unpaid beyond an agreed period is recoursed back to you and the advance is repaid, usually by offsetting against your next drawdown. We'll always talk to you before that point. With embedded finance, we carry the credit risk, so a buyer who doesn't pay is our problem rather than yours.
It depends on the product. Invoice finance is daily interest on what you've drawn, a margin over the Bank of England base rate, and a service fee per invoice. Loans are a fixed monthly repayment, an arrangement fee, and no early repayment penalty. Embedded finance is priced per transaction.
Invoice finance has a 1-year contract term. Loans have a term because you're repaying a fixed sum, but there are no early repayment penalties.
For invoice finance, it depends on our review of your business; where one is needed, we tell you at the point we give you terms, never later. A personal guarantee might apply for a loan. Under the Growth Guarantee Scheme, a lender cannot take your principal private residence as security.
Days rather than weeks for a decision. Once an invoice finance facility is live, an approved invoice is funded within 24 hours.
It varies by product. For invoice finance, we ask for basic financial documents (e.g., your most recent filed accounts, recent management figures, an aged debtors report) and a short conversation about what you're funding. For a business loan, typically just a few months of bank statements. For embedded finance, typically a sample buyer list. Nothing that should take you more than an afternoon.
More funding capacity and more competitive pricing, plus access to Allica's business account, overdraft and asset finance. If you're already a Kriya customer, your facility and your contacts stay as they are.